
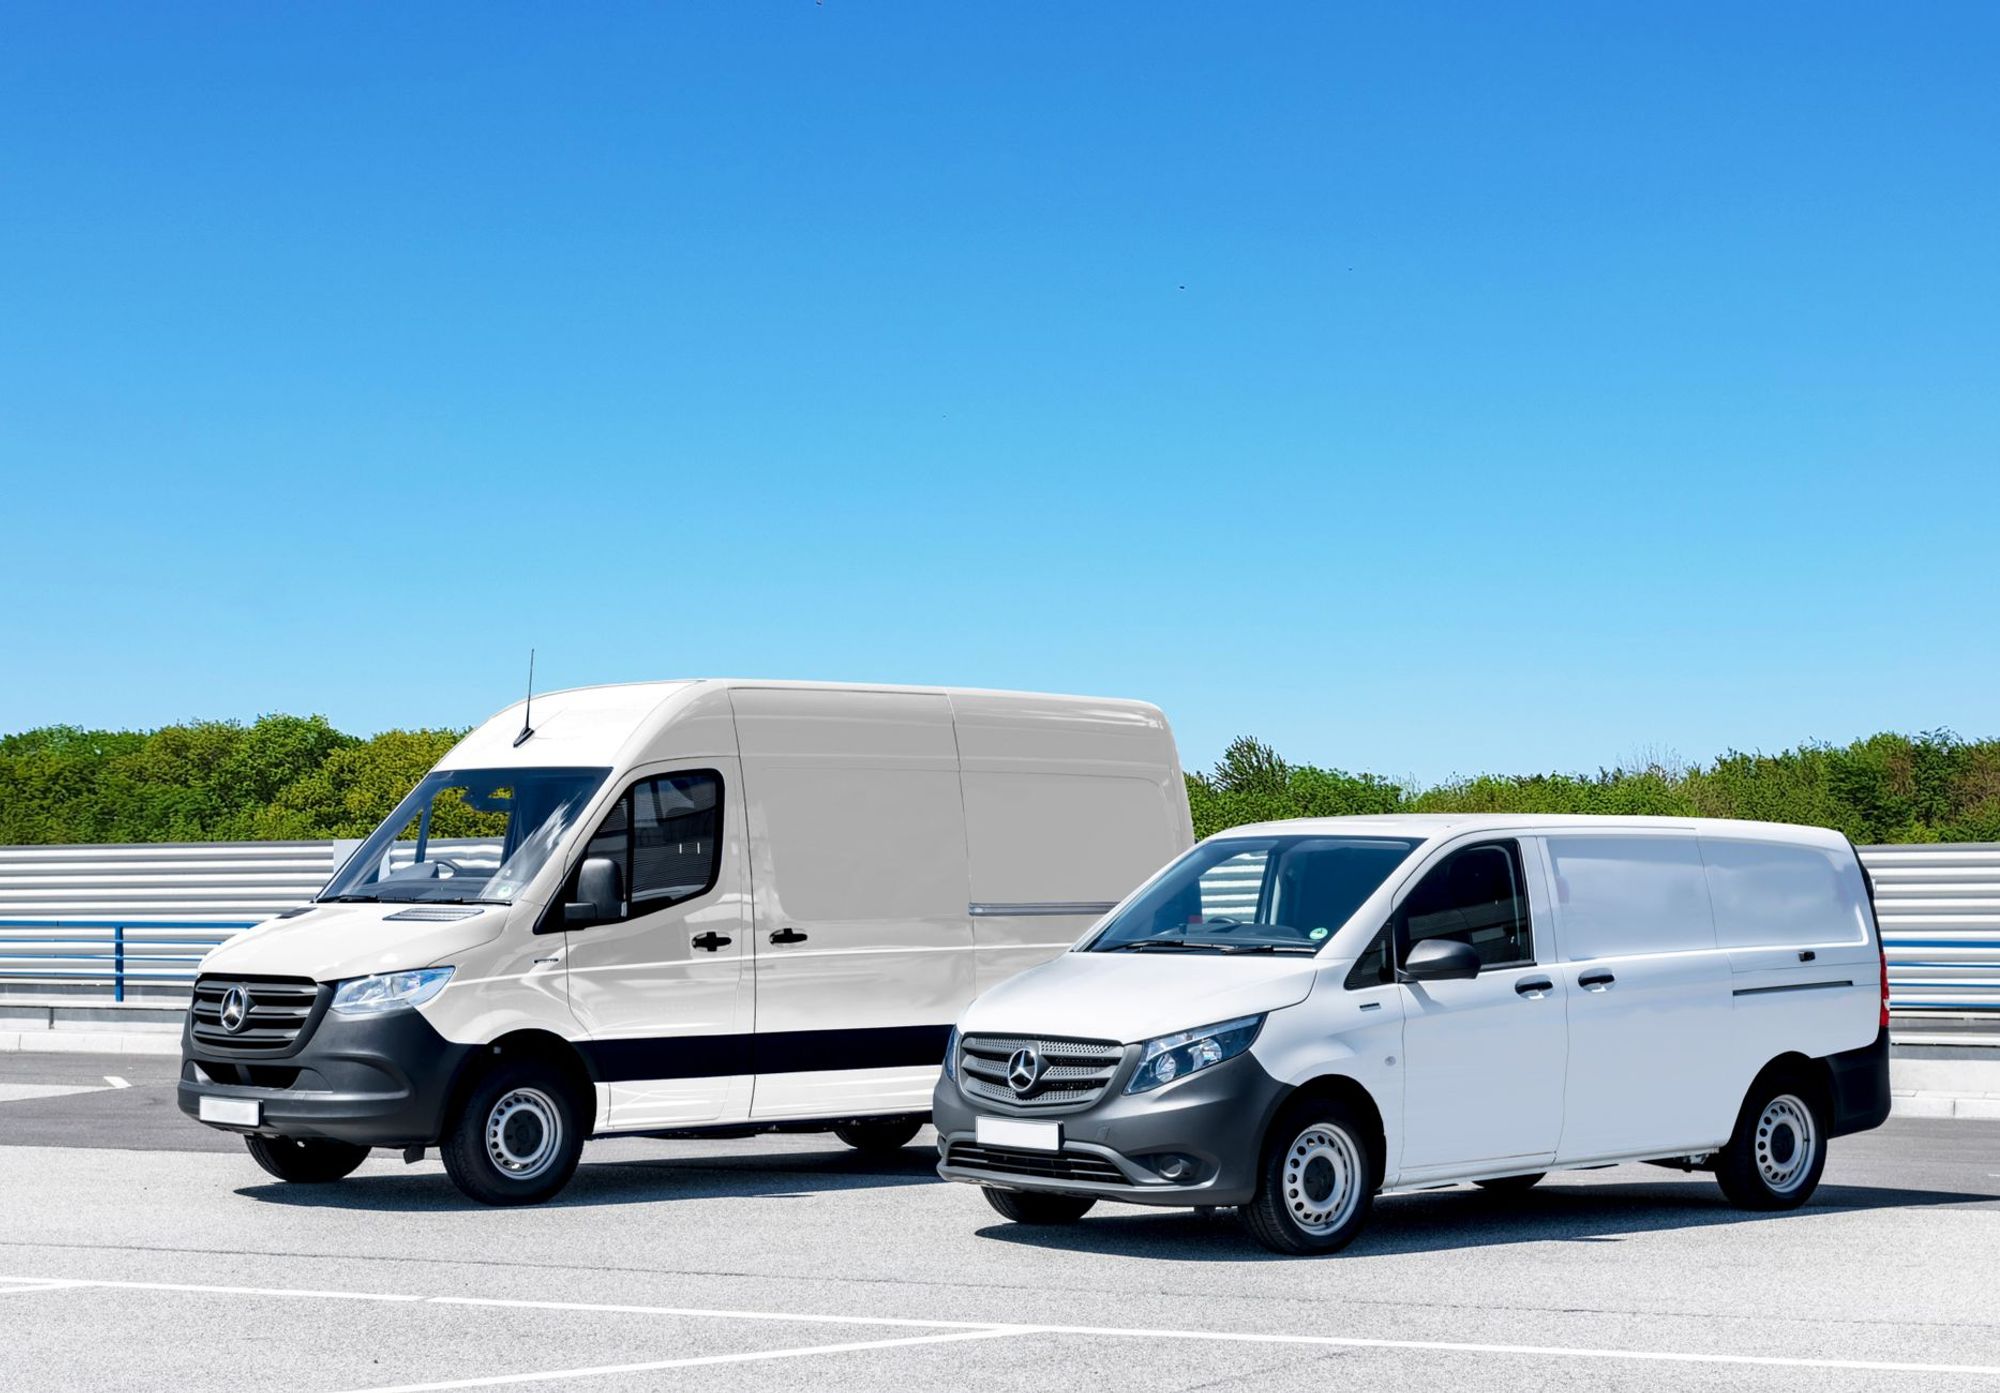
Commercial van and ute finance can help a business buy a working vehicle while spreading the purchase cost. The useful comparison starts with the complete job-ready vehicle, including its fit-out, and the cash the business needs to keep operating. An ABN or a ute badge does not by itself establish eligibility for a commercial loan.
Work out the intended business and private use honestly, then check the appropriate product with the lender. For the wider decision, see commercial asset finance lenders and our business equipment finance service.
Write a working vehicle brief before shopping
List the jobs the vehicle must perform, the people travelling in it and the equipment it will carry. A plumber carrying fittings and tools has different needs from a courier moving parcels or a builder towing a trailer. Record the loads you actually expect rather than selecting a vehicle on appearance or a headline towing figure.
Consider access to customer sites, loading height, parking clearance, security, driver comfort and whether a replacement vehicle could keep the business moving during repairs. If the business works in a city basement or a narrow driveway, the fitted height and turning space can matter as much as the purchase price.
Decide which features are essential now and which can wait. Financing an expensive fit-out that adds little productive value can tie up borrowing capacity and create a larger payout when you want to change vehicles.
Check payload after the fit-out
Ask the supplier for the exact vehicle specification and the weight of the proposed additions. Canopies, shelving, tool drawers, refrigeration, tow equipment, water tanks and accessories all form part of the working setup. Include occupants and the goods you expect to carry when assessing the loaded vehicle.
Have the manufacturer or a qualified specialist confirm that the completed configuration stays within the relevant vehicle and axle limits. If towing is part of the job, assess the loaded vehicle and trailer together. Do not assume a modification gives permission to exceed every other limit. Our existing towing weights guide explains the different measures to check.
This matters to finance because the lender needs an accurate description of its security, while the business needs an asset that can perform the work supporting the repayments. A loan approval cannot make an unsuitable load configuration workable.
Price the vehicle and fit-out separately
Obtain an itemised quote showing the vehicle, accessories, installation, registration and any other charges. If two suppliers are involved, record who supplies each component, delivery dates and the payment sequence. Ask the lender whether the proposed additions can be included in the asset facility and what evidence is required.
Loose tools, consumables and working capital may need different treatment from permanently fitted equipment. Do not assume every item on a dealer package will be funded, or that an aftermarket conversion adds its full cost to resale value. Confirm warranty and insurance treatment with the relevant providers.
For an electric work van or ute, add charger installation, electrical capacity, charging access and route downtime to the operating plan. A purchase discount is only one part of the decision if charging arrangements make the vehicle harder to use.
Separate business use from the tax outcome
Tell the broker how the vehicle will actually be used, including commuting, family trips and weekend use where relevant. Different products have their own business-use requirements. Do not change the stated purpose to fit a preferred loan.
Ask your accountant what records are needed and how the vehicle, business structure and private use affect tax and GST treatment. Budget from the gross cash commitments until that advice is clear. Do not treat a possible tax benefit as cash available for a deposit today, or assume every dual-cab ute receives the same tax treatment.
Keep the borrower, purchaser and invoice details aligned. A vehicle ordered personally but intended for a company can create avoidable settlement questions. Resolve the entity and intended ownership before signing purchase documents.
Compare named commercial finance products
St.George's business car loan is a chattel mortgage for new or used business vehicles. Its published eligibility includes GST registration, an ABN registered for at least two years and mainly business use. The St.George profile also covers other products, whose consumer rates should not be applied to this loan.
CommBank business car and equipment finance offers an equipment loan and discusses tailoring repayment structure. Use the Commonwealth Bank profile as background and request the exact commercial terms.
Pepper's public business-asset guide describes commercial motor vehicles and business equipment. Confirm the proposed van or ute against the current product criteria. Read our Pepper Money profile, then confirm asset and applicant eligibility for the commercial product. A listed product category does not mean that every fit-out or application is accepted.
Compare the complete cash commitment
As an invented purchase-budget example, a van costs $48,000, shelving and installation cost $9,000, and initial setup costs total $3,000. The job-ready outlay is $60,000 before any other costs identified in the final quotes. If the business has $15,000 available but needs $8,000 as an operating reserve, using the whole $15,000 as a deposit would leave it exposed.
Decide what cash must remain available, then ask which costs the lender will finance and obtain a quote for the resulting amount. This is a purchase-budget illustration, not a loan repayment quote or tax calculation.
Compare offers using the same financed amount, deposit, term and balloon. Include establishment and ongoing fees, total contractual payments, early payout terms, security and any guarantee. If an offer has a final balloon, use our commercial balloon guide before accepting a lower regular payment.
Prepare for approval, delivery and replacement
Supply the itemised quote, business details and financial evidence the lender requests. Our commercial finance documents guide helps organise the information. Tell the broker about existing vehicle finance and provide a current payout figure if a trade-in will clear it.
For a used vehicle, arrange an independent inspection and confirm the lender accepts the seller and completed specification. The used equipment finance guide covers the purchase checks that become more important when ownership history is less straightforward.
Before collection, confirm the vehicle and fit-out match the approved documents, insurance is in place as required and the supplier has confirmation of payment. Keep installation records and servicing evidence. They help you maintain the vehicle and explain its condition when selling later.
Send Loanseekers the full vehicle quote, fit-out plan and intended use. That gives us a practical basis for comparing available commercial options for the vehicle your business will actually operate.



