
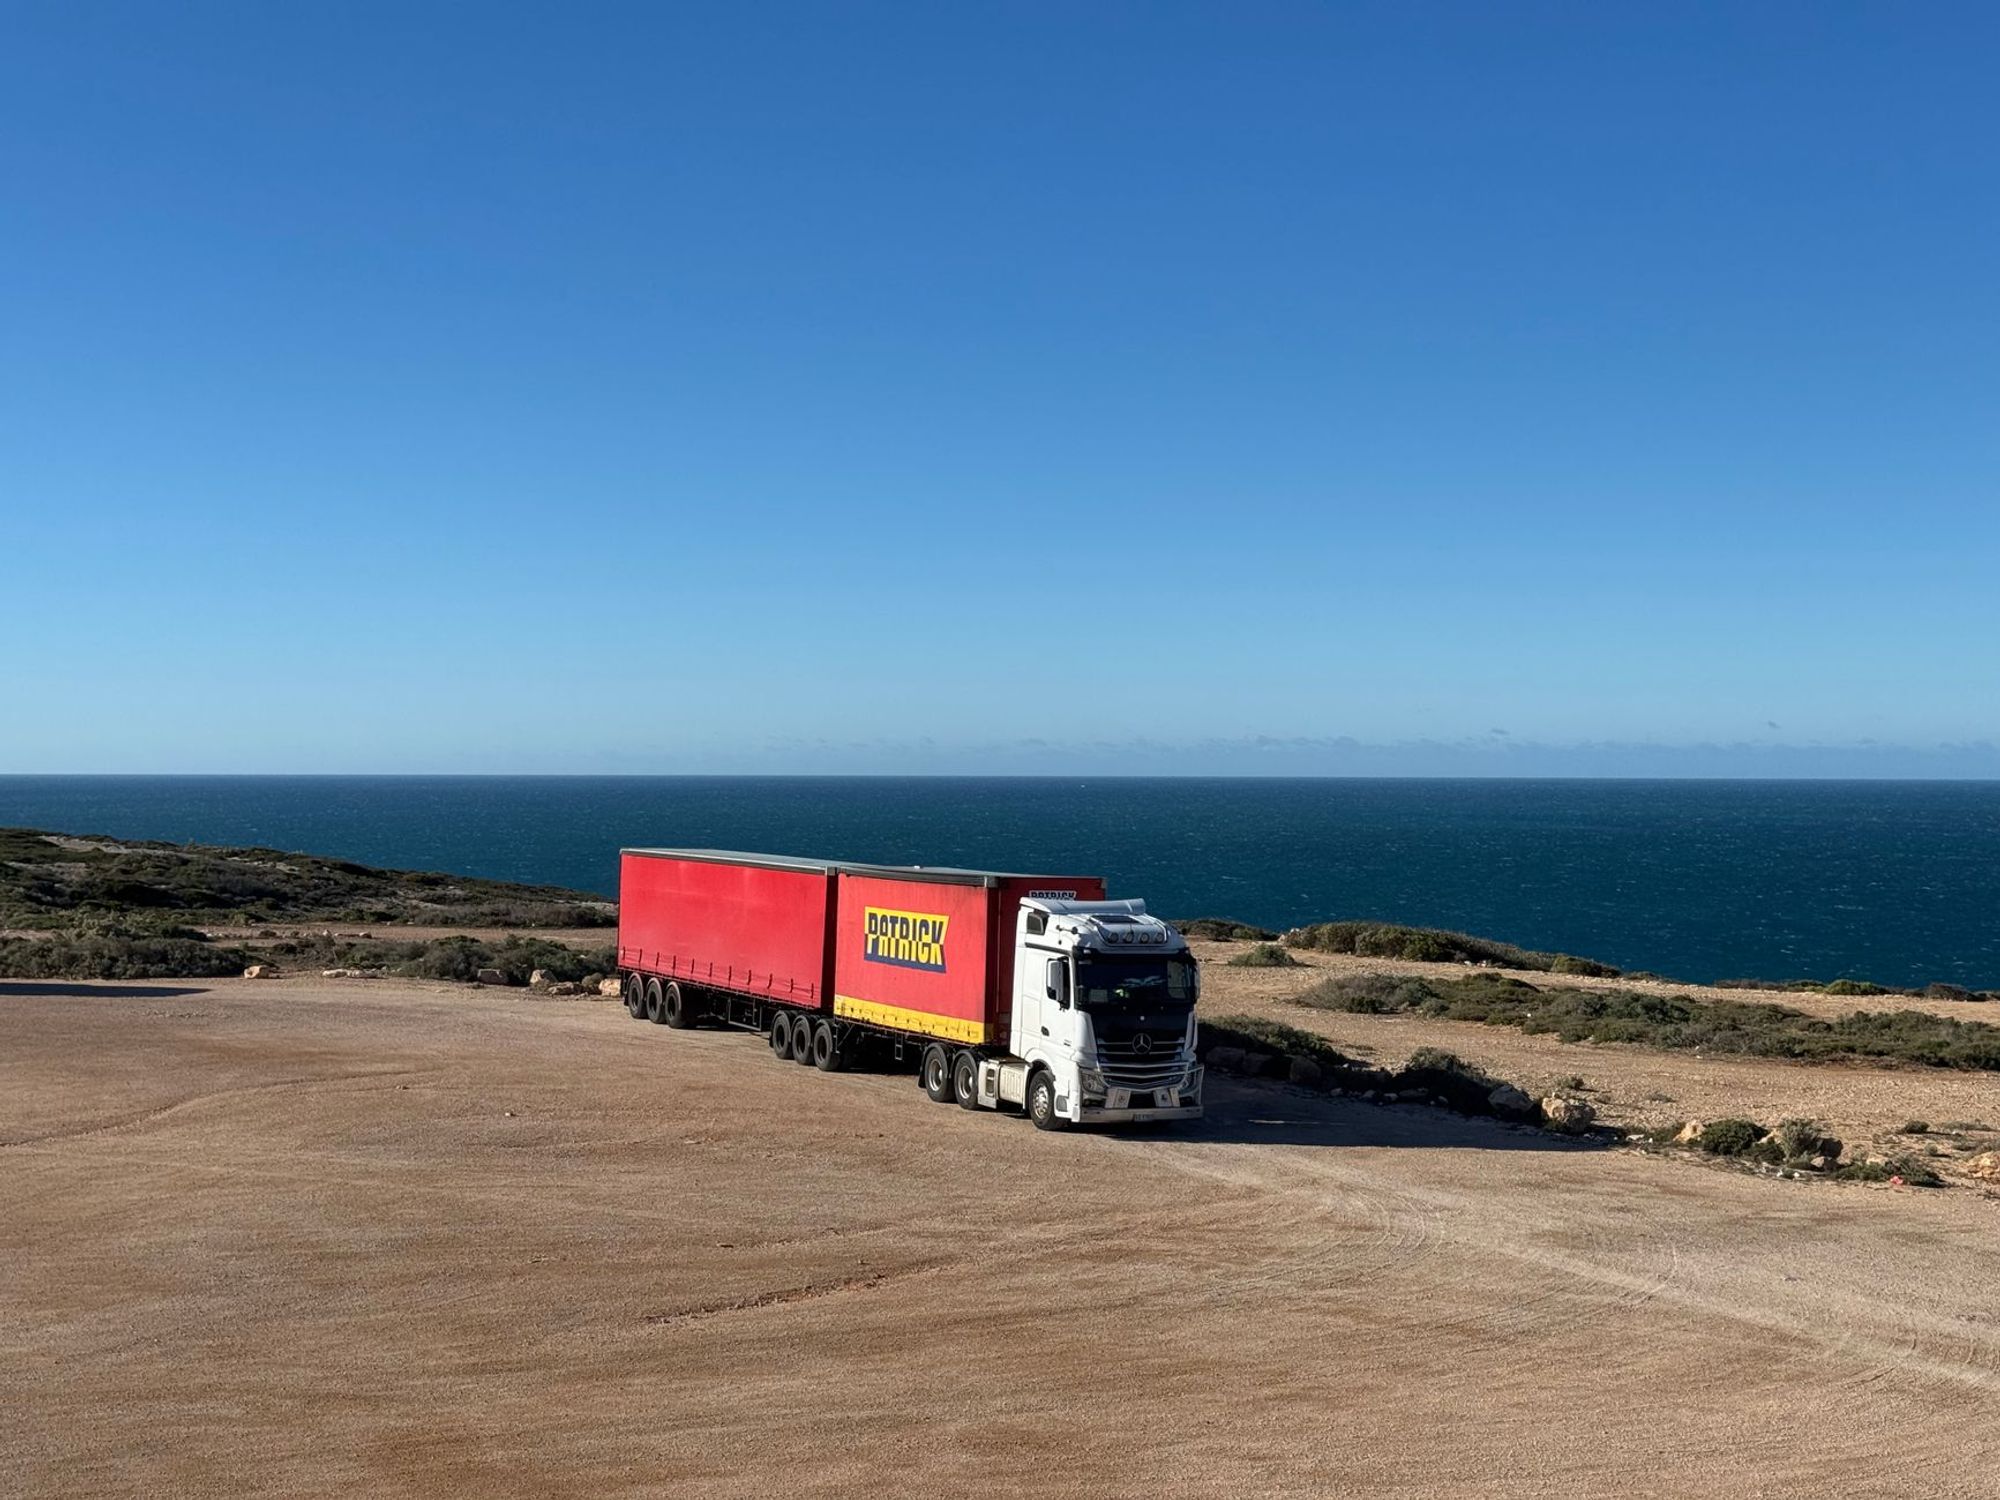
Truck finance for owner drivers starts with two linked questions: can the business support the repayments, and is the truck acceptable security? A freight contract helps explain the income, but the important figure is what remains after operating costs, existing debts and the owner's living needs. Match the finance to the actual vehicle and work before paying a non-refundable deposit.
This guide focuses on an owner-operated transport business. For the wider lender selection process, use our commercial asset finance lender guide. For a prime mover and trailer purchase, also read commercial trailer finance.
Start with the revenue you can demonstrate
Prepare a short description of the work: local deliveries, linehaul, refrigerated freight, civil construction or another activity. Explain whether the truck replaces an existing vehicle, takes over work previously subcontracted, or supports a new contract. Those scenarios have different evidence behind them.
Separate confirmed work from forecasts. A signed contract can still contain cancellation clauses, minimum-service obligations or variable volumes. Show the payment basis, contract duration, who pays fuel surcharges, and whether waiting time, empty return trips and cancelled loads are paid. A quoted hourly rate is not the same as a paid hour for every hour you work.
Reconcile recent invoices with money received in the business account. If one customer supplies most revenue, explain what happens if that account pays late or stops using you. For a first truck, your industry experience and proposed contracts help explain the plan, but do not replace a lender's assessment. Our new business asset finance guide covers that separate situation.
Choose the truck around the job
Give the lender the make, model, build year, kilometres, configuration, purchase price and seller details. Include the body or attachments being purchased, such as a tipper body, crane or refrigerated unit. Ask for separate descriptions and prices where a supplier is combining components.
Check the truck's working capacity with the supplier and an appropriately qualified inspector. Payload, axle configuration, body dimensions, route access and towing requirements affect whether it can do the job that supports the application. The NHVR's general access guidance explains that combinations outside general mass or dimension limits can require a notice or permit. Confirm the rules and access arrangements relevant to your operating jurisdiction and route.
Build a cash budget before choosing a repayment
Include fuel, tyres, scheduled servicing, unexpected repairs, registration, insurance, tolls, parking, bookkeeping, permits and any subcontractor costs. Add existing business commitments and the money you need to draw for household expenses. Treat tax and GST cash movements separately so money reserved for a future obligation is not mistaken for spare cash.
Allow for non-working days. The loan continues when a major service, breakdown, illness or a delayed contract stops the truck earning. A deposit that leaves the business with no repair reserve can make an apparently smaller loan harder to manage.
Consider this invented monthly planning example, not a lender affordability calculation. Cash collected from customers is $24,000 excluding GST. Fuel, servicing, tyres, insurance and other operating costs total $14,000. Existing debt payments, an owner draw and tax reserves use another $6,000. That leaves $4,000 before the proposed truck repayment and any extra contingency. If collections fall to $20,000 while those outgoings remain unchanged, that buffer disappears. Obtain a finance quote and test it against both scenarios before committing.
Compare commercial products, not consumer car rates
NAB's vehicle and equipment finance range expressly includes commercial trucks and offers purchase and lease options. Its Loanseekers lender profile provides wider background, but a truck needs a commercial assessment.
St.George hire purchase includes trucks and trailers; ownership transfers after the required final payment. Review the St.George profile alongside the actual commercial offer.
Pepper Money's public business-asset guide describes commercial motor vehicles, machinery and business equipment. The Pepper Money profile is a starting point for understanding the lender, not a truck rate quote.
These examples identify different product routes. They do not establish which lender will accept your truck, business history, credit position or seller. Ask Loanseekers to confirm current panel access and obtain comparable commercial terms for your exact transaction.
Decide how you want to own and repay the truck
A chattel mortgage finances an asset the business owns, with security over it. Hire purchase and leasing have different ownership arrangements. Read the agreement to understand who owns the truck, when ownership can pass, and what happens when you want to replace or sell it.
Compare the amount financed, deposit, term, fees, repayment timing, security and any personal guarantee. A lower regular repayment may reflect a larger final balloon or longer term. Ask for the total contractual payments and the payout approach if you sell early. Our commercial balloon guide explains how to test the final obligation against a realistic exit plan.
Put the application evidence in one pack
Provide the requested business and identity documents, financial information, bank statements, existing finance commitments, vehicle quotation and any relevant contracts. Make the entity on the quote consistent with the proposed borrower; tell the broker about a company, trust or partnership structure before documents are prepared.
For an existing operator, include the current truck's payout figure if it is being replaced. Show the proposed trade-in separately from that debt. A high trade-in allowance does not tell you how much equity remains after the existing lender is paid. The commercial finance document checklist helps organise the file without guessing a universal document requirement.
Check the settlement sequence before collecting
Confirm any lender conditions, the seller's payment deadline, insurance requirements and how existing finance will be discharged. For a used truck, arrange mechanical and ownership checks before the transaction becomes unconditional. Do not treat a finance discussion or indicative quote as cleared settlement funds.
If you are buying at auction, establish the funding and settlement requirements before bidding. If delivery is delayed, ask whether the approval or quoted terms need refreshing. Arrange the first service and operating reserve as carefully as the first repayment.
Bring Loanseekers the truck quote, your trading history and a realistic operating budget. Our machinery and commercial asset finance team can compare available options around the vehicle, the work and the cash the business must retain.



