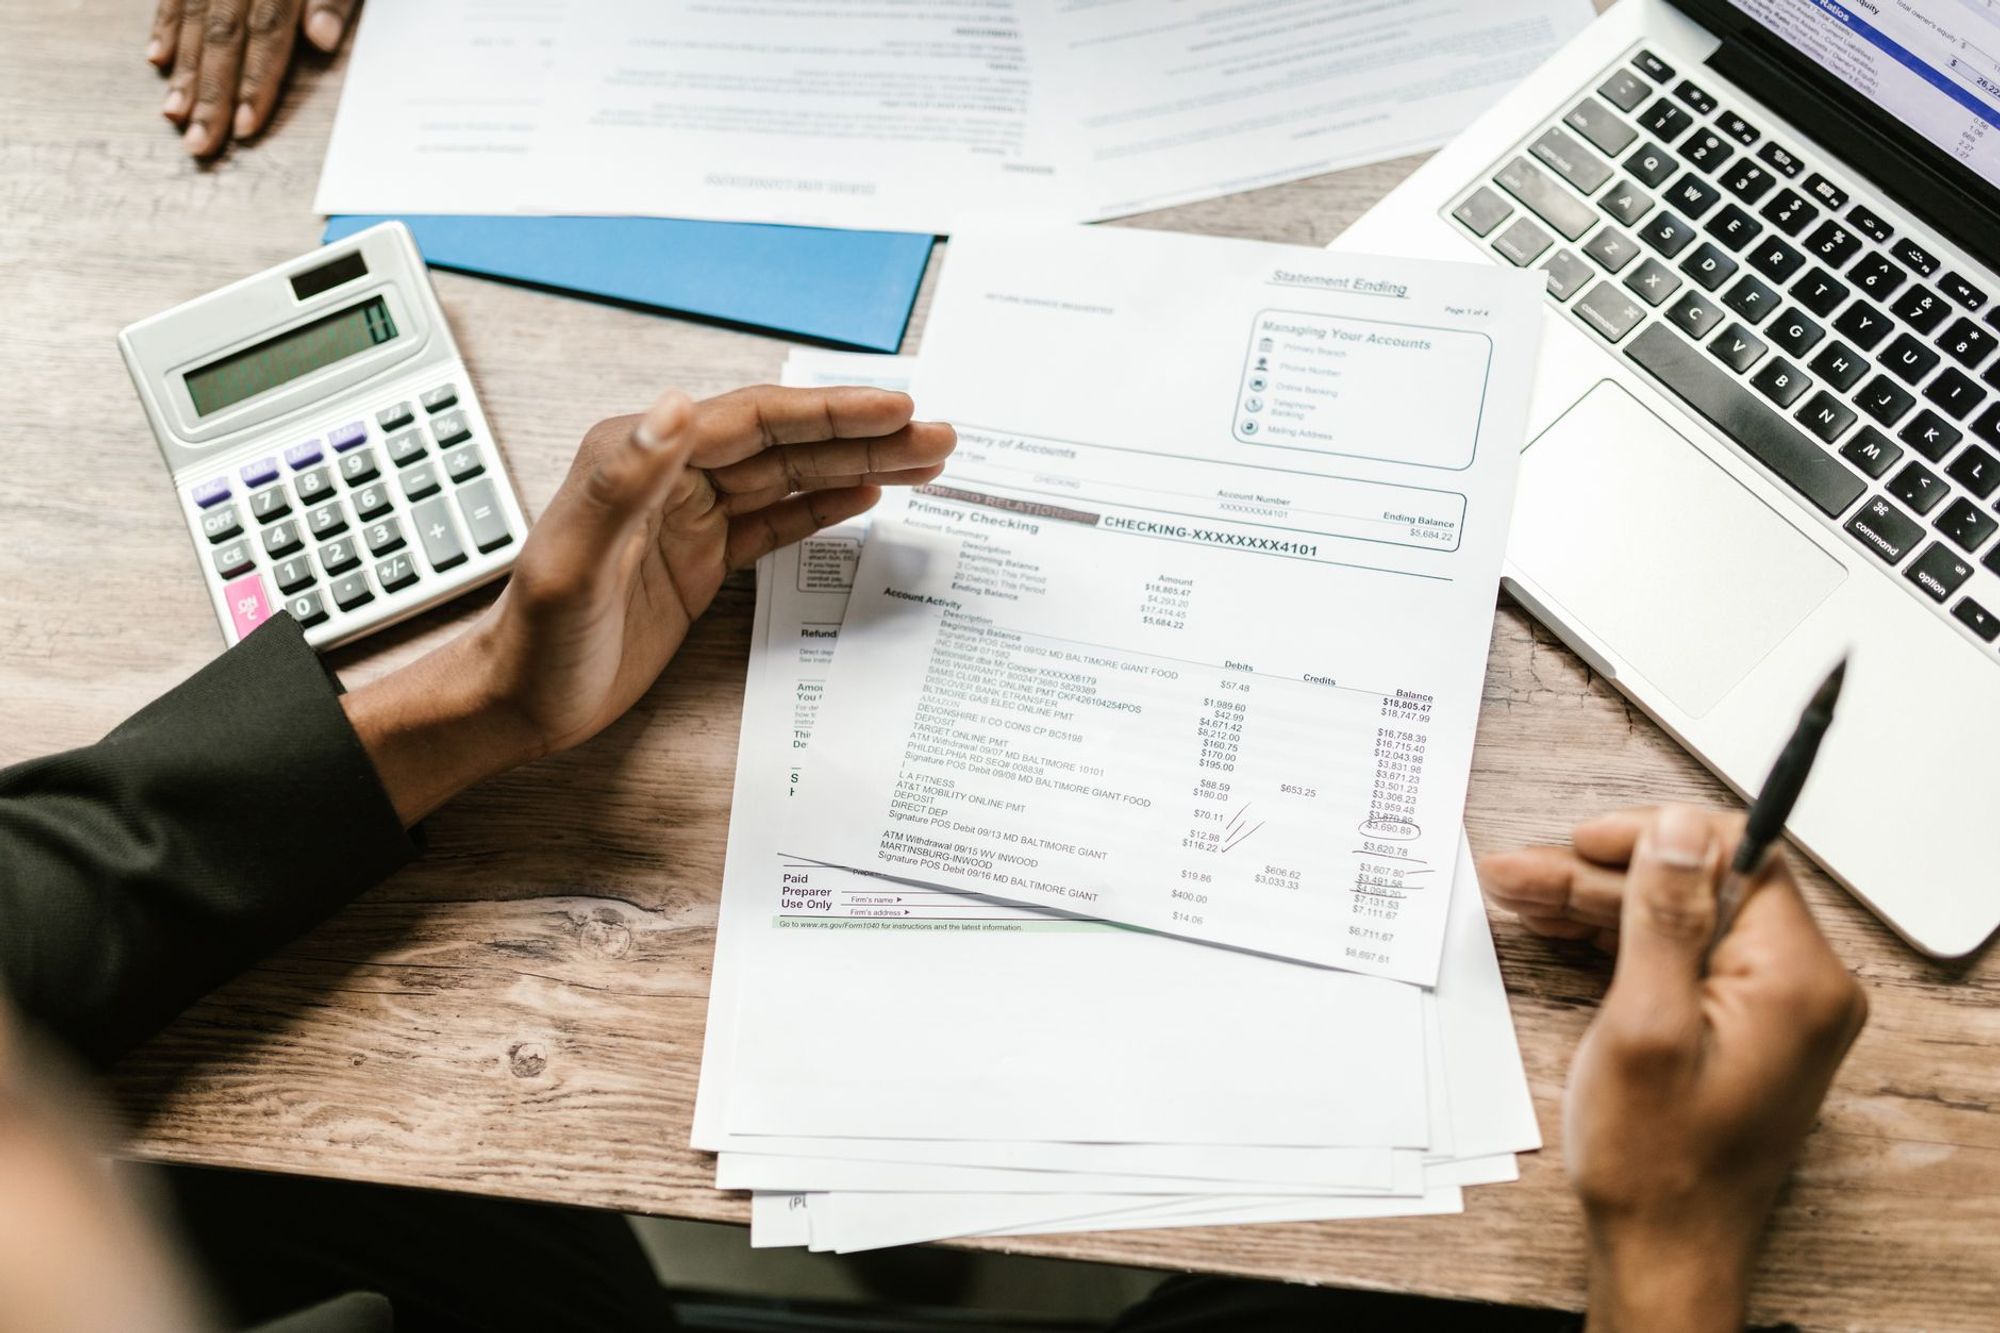
Bank statements are one of the first documents a lender asks for when you apply for car finance, and they reveal far more than your balance. Knowing what a lender is looking for helps you present cleanly and avoid the small issues that can delay or shrink an approval.
Why lenders ask for bank statements
A payslip tells a lender what you earn. Bank statements tell them how you actually live. Lenders usually request the most recent three months of statements for your main transaction account, and sometimes your savings and any accounts where regular commitments are paid. From those pages they verify income, measure spending, check existing debts and look for signs of financial stress. Most lenders now import statements digitally through a secure read only feed, so the picture they see is accurate and hard to dress up at the last minute.
Income and its consistency
The first thing a lender confirms is that the income on your application matches what lands in your account. They look for regular salary credits, the employer name, and whether the amount and timing are steady. Consistent pay over the period supports a stronger application. Irregular income, cash deposits that cannot be traced to an employer, or a recent drop in pay can all prompt questions, particularly for casual, contract or self employed applicants who may need to supply additional evidence.
Self employed and variable income applicants
If your income is not a fixed salary, bank statements carry even more weight, because they are the clearest record of what your business or casual work actually pays you. Lenders will often average your income across the statement period rather than taking the best month, and they may ask for business bank statements, tax returns or notices of assessment alongside your personal accounts. Seasonal dips, large one off invoices and drawings from a business account all get read in context, so keeping business and personal spending in separate accounts makes the picture far easier for an assessor to follow. The cleaner and more consistent the deposits look, the less back and forth the application needs.
Living expenses and spending patterns
Lenders total your everyday spending to work out the surplus available for a new repayment. They categorise groceries, transport, utilities, insurance, subscriptions, dining and other outgoings, then compare the result against a benchmark and generally use the higher figure. This is where day to day habits matter. Heavy discretionary spending narrows your assessable surplus and can lower the amount you are approved for. You can model how a given repayment fits your budget using the repayment calculators.
Existing debts and commitments
Your statements show the loans and cards you are already servicing. Regular repayments to other lenders, credit card minimums, personal loans and buy now pay later instalments all count toward your commitments. Frequent buy now pay later use is a particular focus, because it signals reliance on short term credit even when each amount is small. Reducing or closing these before you apply lifts your surplus and simplifies the assessment.
The red flags lenders watch for
Certain patterns stand out and can slow an approval or lead to a decline. These include dishonoured or missed direct debits, an account that is regularly overdrawn, late payments to other lenders, and existing debt collection or hardship arrangements. Gambling transactions are not an automatic decline, but frequent or large betting relative to income will draw scrutiny, because it affects both surplus and risk. A pattern of last minute transfers to cover repayments suggests a tight budget, which lenders weigh carefully.
How to prepare your statements
A little preparation goes a long way. Give yourself two to three months of clean, consistent statements before you apply, since lenders focus on recent activity. In that window, avoid new buy now pay later accounts, keep your main account out of overdraft, and make sure every regular repayment clears on time. Cancelling unused subscriptions and avoiding one off splurges presents a leaner, more predictable budget. If you have had an unusual transaction, such as a large one off deposit or an emergency expense, being ready to explain it removes a potential query.
What a clean set of statements unlocks
Presenting well kept statements does more than smooth the approval. It can widen your borrowing power and, in some cases, help you access a sharper rate, because a lower risk profile is rewarded. It also speeds things up. When the digital feed shows steady income, controlled spending and no red flags, a lender can move to approval faster. Our guide to boosting your car loan approval odds covers the wider picture, and getting a pre-approval first lets you shop with a firm budget.
Comparing lenders once you are ready
Different lenders weigh statements differently. Some are more comfortable with variable income or a past blemish, while others reward a spotless file with a lower rate. Comparing the current car loan rates and the lender panel once your statements are in good shape helps you match your profile to the right lender rather than accepting the first offer. If you are refinancing an existing car loan, the same statement discipline applies, and our refinancing guide explains what to expect.
Bank statements are simply a record of how you manage money. Treat the months before an application as a chance to make that record as clean and clear as possible, and the rest of the process becomes far easier.