
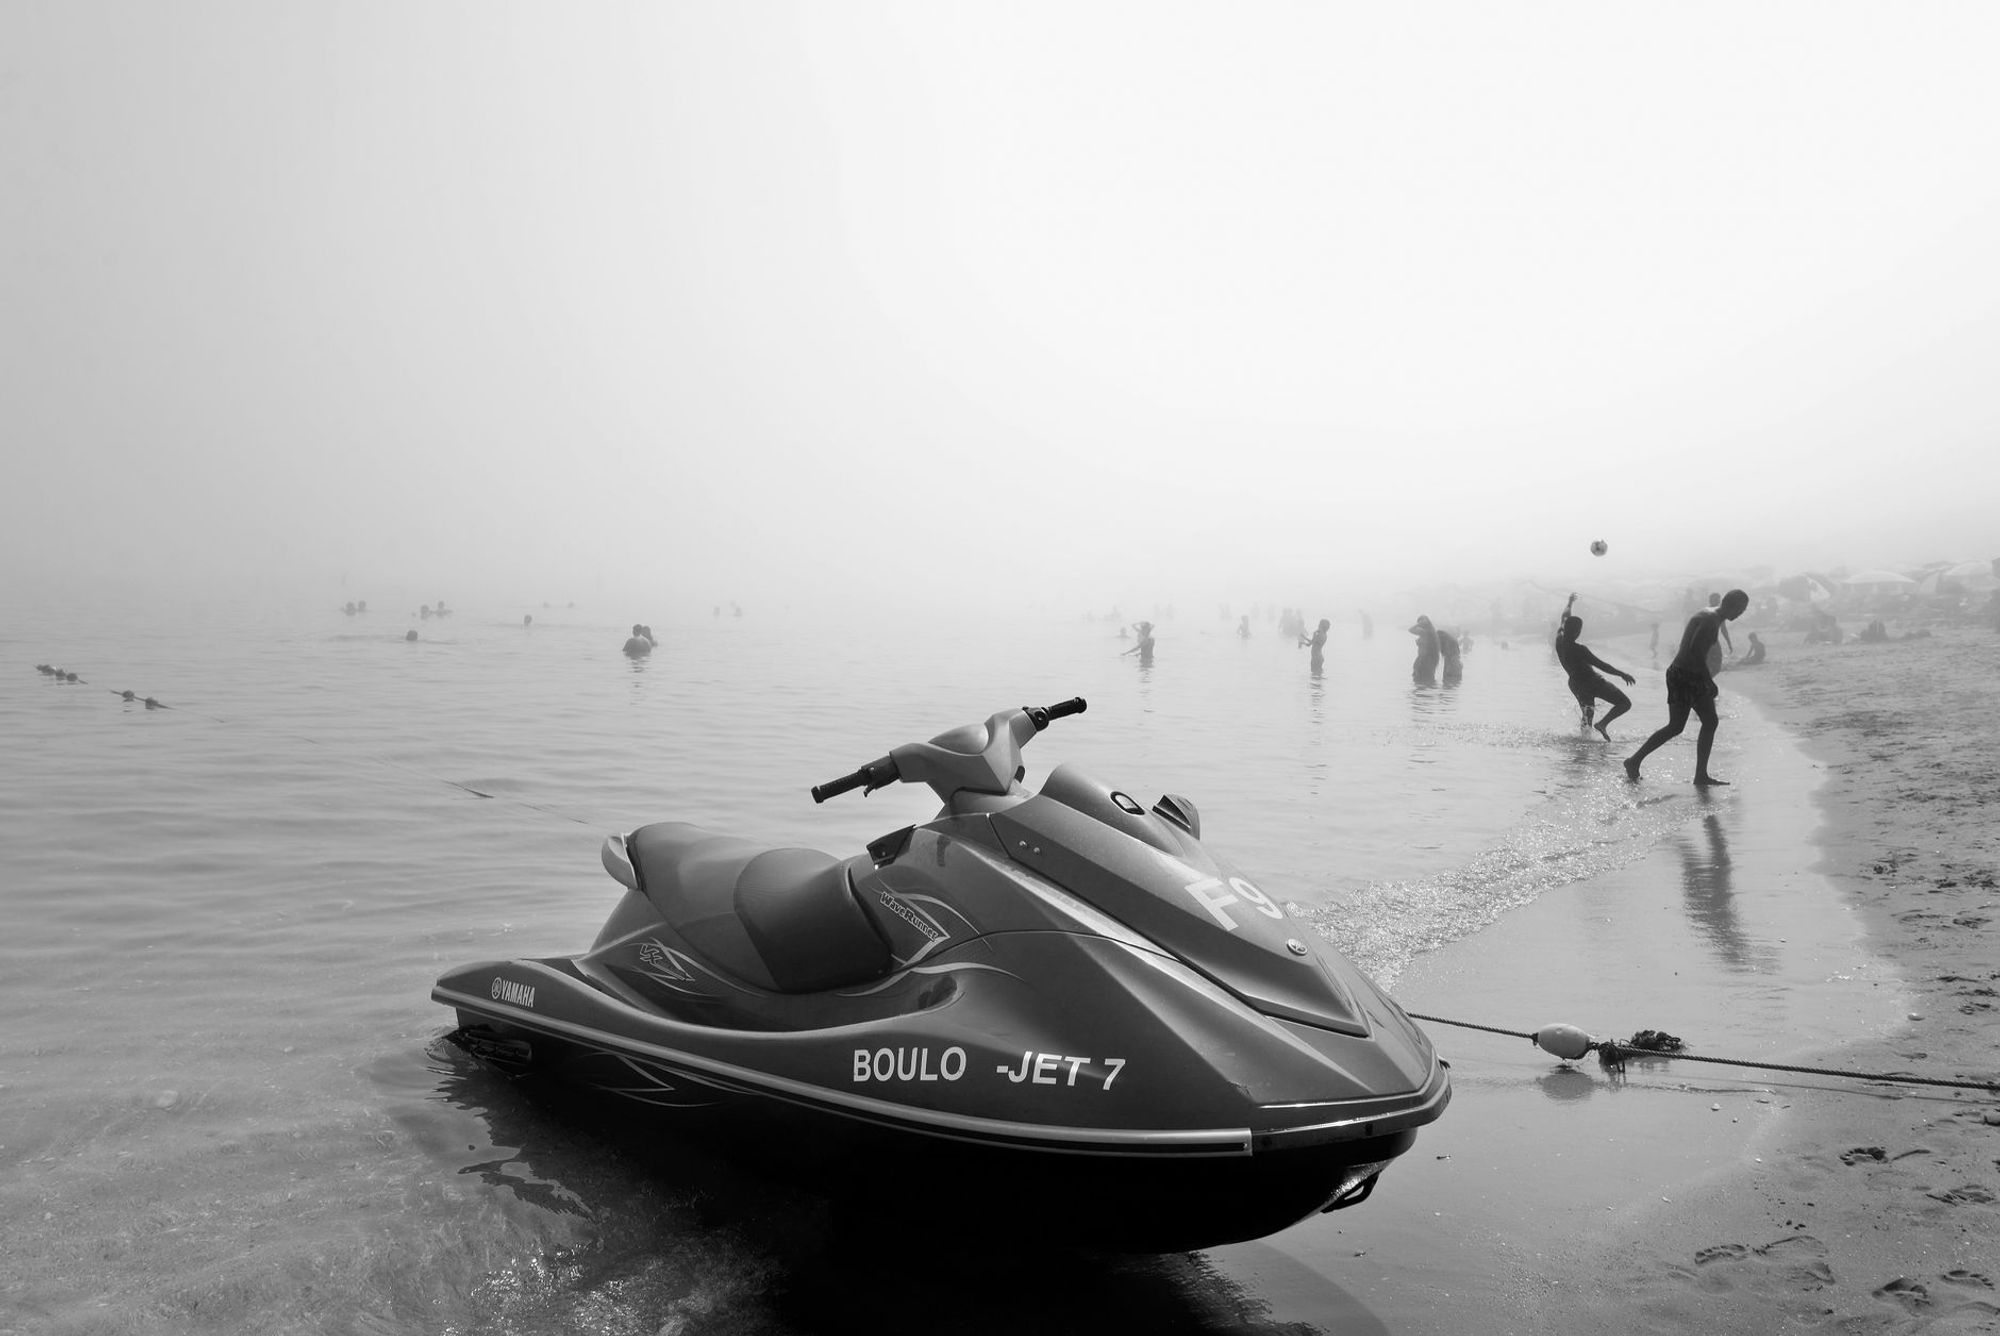
A jet ski sits in an awkward spot for lenders. It is a registered, serial-numbered asset that can be repossessed and resold, which makes it look like a car. It is also a discretionary purchase that gets used a dozen weekends a year, which makes it look like a holiday.
That tension explains almost everything about how personal watercraft finance actually works in Australia, including why two applicants with the same income can be offered very different structures.
The lender is asking a different question than you are
You are asking what the repayment is. The lender is asking what the ski is worth if you stop paying, and how quickly it could turn that into cash.
A late-model ski from a mainstream brand with a clean registration and a trailer is a straightforward answer. It has a hull identification number, an established resale market, and a clear value. That is a security a lender can lend against.
An older ski, a heavily modified one, or a stand-up model with a thin resale market is a harder answer. The security is worth less and moves slower, so lenders either price for that or decline to take the ski as security at all.
Secured or unsecured: the fork in the road
Almost every personal watercraft application resolves into one of two structures.
- A secured loan. The ski itself is the security, registered as a security interest against its HIN. Because the lender has something to fall back on, secured structures generally carry the lower rate of the two. The trade off is that lenders apply asset criteria: age limits, condition, and often a requirement that the ski is comprehensively insured for the life of the loan.
- An unsecured personal loan. No asset is taken as security, so the lender is relying entirely on you. Criteria are looser about what you buy, which is why this route often suits an older ski, a private sale, or a purchase that includes a trailer and gear as one lump. The rate is typically higher, because the lender is carrying more risk.
Neither is automatically the right answer. A three year old ski bought from a dealer is usually a secured conversation. A ten year old ski bought from a Facebook listing is usually an unsecured one. Our personal loans guide covers how unsecured pricing is put together if that is the direction you land in.
What a lender actually assesses
The asset is only half of it. The other half is you, and the checks are the same ones that apply to any consumer credit application under responsible lending obligations.
- Income and stability. Not just how much, but how reliably. Lenders look at employment type and how long you have been there.
- Existing commitments. Rent or mortgage, other loans, credit card limits (the limit counts, not the balance), and any buy now pay later facilities.
- Credit file. Repayment history on existing accounts, and any defaults or enquiries. A run of recent applications reads as pressure even if none of them settled.
- Living expenses. Declared and benchmarked. A discretionary purchase invites more scrutiny here than a work vehicle does.
Approval is never a certainty and no lender can promise it in advance, but the strongest thing you control is presenting a clean, consistent three months of banking. If your credit file is the weak point, boosting your approval odds covers the practical fixes that actually move the needle.
The costs that never appear on the sticker
Buyers routinely finance the ski and then get surprised by the ownership. Budget for these before you decide how much to borrow, not after.
- The trailer. A ski without a trailer is a ski you cannot move. Registered trailers have their own compliance and rego.
- Registration. Both the watercraft and the trailer are registered, and the rules and fees are set by each state or territory, not nationally.
- Licensing. Operating a personal watercraft requires the relevant licence in most jurisdictions, and several states have PWC-specific endorsements on top of a general boat licence. Check your own state before you buy, because the requirement is not uniform.
- Insurance. If your loan is secured against the ski, comprehensive cover is usually a condition, not an option.
- Storage. A ski on a trailer takes up a garage bay. Paid storage is a real monthly line item for a lot of owners.
- Servicing and winterisation. Two stroke and four stroke skis both want regular servicing, and salt water use adds flushing and corrosion maintenance.
If you are buying used, run the PPSR search first
This is the single cheapest piece of protection in the entire purchase. A search of the Personal Property Securities Register costs $2 online, GST does not apply, and the search certificate is included in that fee.
For a personal watercraft you search by HIN, the hull identification number, which is the nautical equivalent of a car's VIN. It is usually a 14 character code that identifies the country, manufacturer, serial number and date of manufacture. Find it physically on the hull and search that number, not the number the seller texts you.
What the search tells you is whether anyone has registered a security interest against that hull. If a previous owner financed the ski and still owes money on it, the lender's interest can survive the sale, which means the ski can be repossessed from you after you have paid for it. The certificate is your legal record that you checked.
Two dollars against a five figure purchase is not a decision that needs thinking about.
Financing the ski, the trailer and the tow vehicle together
If you are buying the whole setup at once, do not automatically split it into three applications. Every separate application leaves a mark on your credit file, and three enquiries in a fortnight reads worse than one.
A single loan sized to the whole package is often cleaner, and if the tow vehicle is the piece you are missing, a car loan sized properly around the ski and trailer weight is usually the better sequence than buying a car first and discovering it cannot tow.
Where a broker changes the outcome
Personal watercraft is a niche where lender policy varies enormously. Some lenders will not take a ski as security at all. Some will, but only up to a certain age. Some treat it as marine, some as a general leisure asset, and the two categories can be priced differently at the same lender.
That variation is exactly why shopping it matters. Loanseekers compares more than 70 lenders and knows which ones actually write personal watercraft rather than quietly declining it after a week. One application, one credit enquiry, and the policy filtering done before anything hits your file.
Ready to see what your setup looks like? Start with the boat and marine finance page, or run the numbers first with our repayment calculator.
